How the 10-Year Treasury Impacts Mortgage Rates and Real Estate
Real Estate, Mortgage Rates, 10 Year Treasury, Homebuyers, Investors
The 10 Year Treasury Just Jumped Over 5%: What It Means for Real Estate and Your Money
The 10-year U.S. Treasury yield is one of the most important indicators to watch when trying to understand where mortgage rates may be headed.
While mortgage rates do not move one-for-one with the 10-year Treasury, they generally have a strong relationship. The mortgage rate is influenced by the 10-year Treasury yield plus a mortgage-market spread that changes based on factors such as interest-rate volatility, market conditions, and investor demand. The Federal Reserve Bank of Boston and Dallas Fed both highlight this relationship.
That distinction matters for homebuyers and real estate investors. A Federal Reserve rate cut does not automatically mean mortgage rates will fall. If the 10-year Treasury rises, mortgage rates can remain elevated or even increase despite changes in the federal funds rate.
As of September 2026, the 10-year Treasury has been around the 5% level, illustrating why long-term Treasury yields remain an important factor for today's mortgage market.
1. What History Tells Us When the 10 Year Hits 5%
The 10-year Treasury is often called the “anchor” for long-term borrowing costs. Mortgage rates do not move in perfect lockstep, but they closely follow the trend. The last time we consistently saw 10-year yields around 5% was before the 2008 financial crisis, and briefly again in late 2023. Historically, these spikes have occurred in periods of:
Higher inflation expectations – investors demand more yield to compensate for future price increases.
Uncertainty about Federal Reserve policy – markets reprice how “high for longer” rates might be.
Stronger growth or heavy government borrowing – pushing yields up as investors require better returns.
Today, the 10 year has climbed from just under 5% to above that level within days, with weekly averages near 5.0% and intraday moves over 5.1%–5.2%, based on Federal Reserve and market tracking data. History suggests two key lessons for real estate professionals and consumers:
Mortgage rates can overshoot in the short term and then settle as markets digest new information.
Housing markets adjust gradually, not overnight—through slower sales, price moderation, and creative financing rather than an immediate collapse.
So does this kind of spike automatically mean a housing crash is coming? Historically, the answer has been no. In past cycles where the 10-year moved quickly higher—such as the mid 1990s or mid-2000s home prices did not instantly fall off a cliff nationwide. Instead, you typically saw a cooling period: fewer bidding wars, longer days on market, and some local price softness, especially in overheated or highly leveraged segments. The 2008 crisis was driven less by the 10-year itself and more by loose lending standards, speculative behavior, and excessive leverage layered on top of a changing rate environment.
As for why the 10-year has shot up so fast this time, several forces are working together: markets are repricing the idea that the Federal Reserve may keep its policy rate “higher for longer,” inflation has been sticky in certain categories, and the federal government is issuing a large amount of new debt that investors demand higher yields to absorb. When you combine those factors with algorithmic trading and global investors repositioning portfolios in real time, moves that used to take months can now happen in days. The key is to separate the speed of the move; which can feel scary from the underlying data, which still points to a slow adjustment in housing rather than an immediate, broad based crash.
📌 Key Takeaway: A 10 year yield above 5% is rare but not unprecedented. It is a signal to plan strategically, not to panic.
2. How This Plays Out for Real Estate and Mortgage Markets
For real estate agents, investors, and loan officers, the 10 year Treasury is effectively the starting point for 30 year fixed mortgage pricing. When the 10 year moves above 5%, it is common to see mortgage rates that are 1.5–3 percentage points higher, depending on credit profile, loan type, and lender margins.
Residential demand: Higher payments reduce affordability, especially for first time buyers. Some will delay purchases, others will adjust and “buy down” their price range or consider different locations that offer more value for the same monthly payment.
Inventory dynamics: Many existing homeowners are locked into 3–4% mortgages. They are reluctant to sell and trade into a 7–8% rate, which can keep inventory tight even as demand cools. This “rate lock in” effect is one of the reasons many markets still feel competitive, even though affordability has worsened.
Investors: As Treasuries yield around 5% with virtually no credit risk, some capital rotates out of leveraged real estate deals, especially marginal or highly speculative projects. Cap rates tend to drift higher, pressuring valuations and forcing investors to underwrite more conservatively, with tighter assumptions on rent growth and exit prices.
Commercial real estate is also feeling the pressure from higher Treasury yields. Office buildings that were already struggling with vacancy and remote work trends now face higher refinancing costs. Multifamily operators who financed aggressively with floating-rate debt are watching their interest expenses climb, which can squeeze cash flow and force difficult decisions about capital improvements or rent increases. Even industrial and logistics properties, which have been strong performers, are not completely insulated from the higher cost of capital.
For real estate professionals, this environment demands more education and clearer communication with clients. Buyers, sellers, and investors need to understand not only where rates are today, but also how they got here and what could realistically happen next. Explaining the relationship between the 10-year Treasury, inflation expectations, Federal Reserve policy, and mortgage pricing can turn confusion into confidence and help clients make decisions that match their time horizon and risk tolerance.
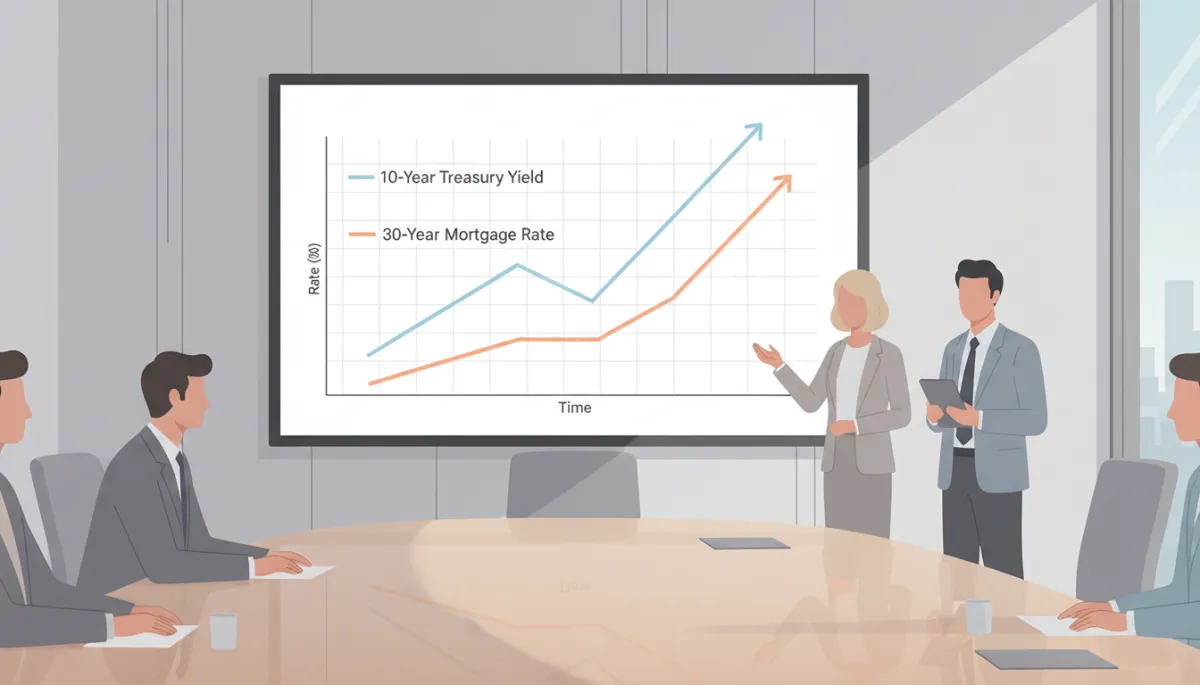
Aligning strategy with rate trends helps agents, investors, and buyers act decisively.
For a mortgage broker like MortgageToday LLC, this environment is where independent guidance matters most. Different lenders react differently to volatility. Some widen margins and price conservatively, while others stay aggressive to win business. Shopping across multiple lenders can easily mean a difference of tens of thousands of dollars over the life of a loan, especially for borrowers in higher-cost states such as California, Texas, Florida, and Arizona where loan sizes are often larger, and small rate differences compound over time.
An experienced independent broker can also help you understand how various loan products behave when rates are moving quickly. For example, a conventional 30 year fixed loan, a Federal Housing Administration loan, and a jumbo loan from a portfolio lender may all be priced off the same 10 year benchmark, but each product has its own guidelines, pricing adjustments, and long term pros and cons. Having someone in your corner who is not tied to a single bank’s product menu can make it easier to compare options side by side and see which structure truly fits your situation.
3. Practical Tips for Homebuyers in a High Rate Market
If you are a homebuyer (or advising one), high rates do not automatically mean “do nothing.” They do mean you should be more intentional. Here are focused, professional strategies that align with a real world, numbers first approach:
Strengthen your file: Improve your credit score, pay down revolving debt, and document income clearly. Stronger files get better pricing, especially on conventional, Federal Housing Administration, Veterans Affairs, and jumbo products. In some cases, a small bump in your credit score can move you into a better pricing tier and save you a meaningful amount over the life of the loan.
Consider term and structure, not just rate: Adjustable-rate mortgages, temporary 2- 1 buydowns, and seller-paid points can create meaningful payment relief when used correctly and explained transparently. These tools are not one size fits all, but for buyers who expect to move or refinance within a certain time frame, they can be powerful ways to bridge the gap between today’s rates and tomorrow’s opportunities.
Be realistic about budget: Build your payment around what is comfortable, not simply what you are approved for. Include taxes, insurance, homeowners association dues, and maintenance in your calculations. In markets like Texas and Florida, property taxes and insurance can vary widely, so it is essential to look at the full monthly payment rather than focusing only on the principal and interest line.
Negotiate more than just price: In many markets, you can negotiate closing costs, rate buydowns, or repairs. That flexibility can matter more than squeezing another one or two percent off list price. A seller credit that funds a permanent buydown or a temporary 2 1 buydown can lower your monthly payment in a way that has a bigger impact on your budget than a small reduction in purchase price.
It is also worth thinking about your time horizon. If you plan to stay in a home for five to ten years or longer, the decision framework is different than if you expect to move again in just a few years. A longer time horizon can give you more room to ride out rate cycles and potential price volatility, while a shorter horizon might make flexible loan structures or lower-cost entry strategies more attractive. A thoughtful conversation with a knowledgeable mortgage professional can help you match your financing to your life plans instead of treating the mortgage as a one size fits all product.
Pro Tip: Work with a broker who will model multiple scenarios—fixed versus adjustable, buy-downs, and different down payments—so you see the full picture before you commit. Clear side by side comparisons can turn an overwhelming decision into a straightforward choice based on numbers and priorities.
4. How the Average Person Can Get Ahead Financially Right Now
Rising Treasury yields are not only a headwind, they are also an opportunity. Here is how the average person—whether buying soon or not—can use this moment to move ahead financially and build a stronger foundation for future decisions:
Upgrade your cash strategy: Higher yields mean better returns on high yield savings, certificates of deposit, and Treasuries themselves. Make sure your emergency fund is earning something meaningful, not sitting in a near zero account. Even a modest increase in yield, when applied to several months of living expenses, can add up over time and help offset some of the sting of higher borrowing costs elsewhere in your financial life.
Clean up your debt profile: High rate credit cards and personal loans become even more painful as rates rise. Prioritize paying those down or consolidating strategically before taking on a new mortgage. Lenders look closely at your overall debt picture, so improving this area can not only reduce stress but also improve your chances of qualifying for better mortgage terms when the time comes.
Prepare for the next refinance window: If you must buy now at a higher rate, plan ahead. Keep your credit strong, maintain stable income, and avoid unnecessary new debt so you are ready to refinance when rates normalize. Think of your current loan as a bridge that gets you into the right home, with a plan to improve your financing when the market offers a better opportunity. Having your documentation organized and your financial profile polished can make that future refinance smoother and more cost effective.
Stay informed, not reactive: Track broad trends—10 year yields, inflation, Federal Reserve policy—but avoid trying to “time the bottom.” Focus on whether a given home and payment make sense for your long term life and financial goals. Markets move in cycles, and there will always be headlines suggesting that now is either the best or worst possible time to act. Grounding your decisions in your own numbers and priorities is far more powerful than chasing perfect timing.
For many people, this is also a good moment to revisit broader financial planning questions. Are you saving enough for retirement, college, or other long term goals. Is your insurance coverage appropriate for your stage of life. Does your investment mix reflect your real risk tolerance, or has it drifted over time. Looking at your mortgage decision in the context of your entire financial picture can reveal trade offs and opportunities that are not visible when you focus on the interest rate alone.
FAQ section
Does the 10-year Treasury determine mortgage rates?
No. Mortgage rates are not directly set by the 10-year Treasury. However, the 10-year Treasury is an important benchmark for long-term borrowing costs and mortgage pricing.
Do mortgage rates follow the 10-year Treasury?
Mortgage rates often move in the same general direction as the 10-year Treasury, but the relationship is not one-to-one. The spread between Treasury yields and mortgage rates can change significantly depending on market conditions.
Will a Fed rate cut lower mortgage rates?
Not necessarily. Mortgage rates are influenced heavily by longer-term market rates, particularly the 10-year Treasury, rather than simply the overnight federal funds rate.
What happens to home prices when mortgage rates rise?
Higher mortgage rates generally increase borrowing costs and can reduce the purchasing power of buyers. The effect on home prices varies by market because inventory, income, housing supply, and local demand also matter.
Should I wait for the 10-year Treasury to fall before buying a home?
There is no guarantee that Treasury yields or mortgage rates will move in a particular direction. Buyers should evaluate the payment, loan costs, expected time in the property, and their overall financial circumstances rather than relying on a single market indicator.
Next step: If you are unsure how these rate moves affect your specific situation, take time to walk through your options with a knowledgeable professional. A short, no-pressure “Mortgage 101” conversation with MortgageToday can help you understand different loan types, payment scenarios, and common pitfalls whether you decide to buy now, wait, or refinance later, you are doing it with clarity instead of guesswork. Schedule a free consultation to get real mortgage advice tailored to your situation and move forward with confidence.
